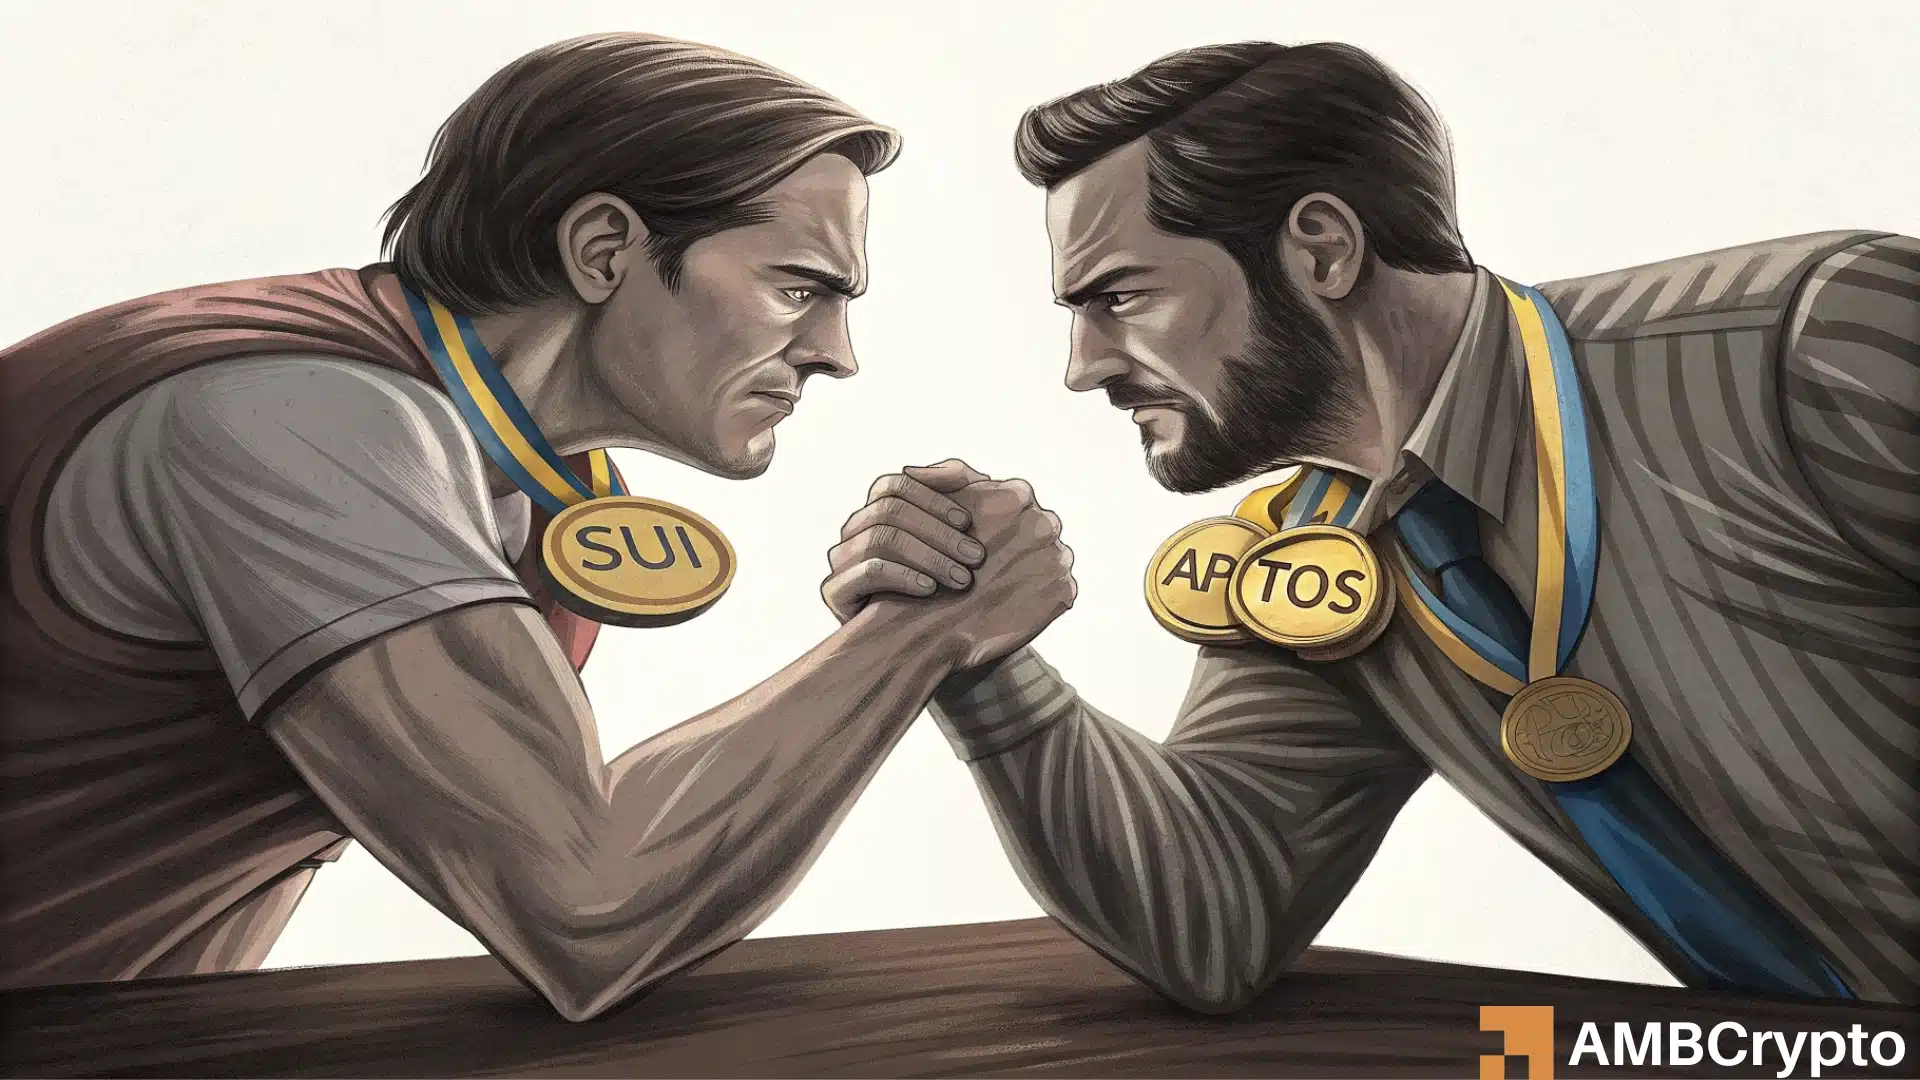
The landscape of Layer 1 (L1) blockchain infrastructure is currently defined by a high-stakes competition for developer mindshare and ecosystem liquidity. As the industry matures, the focus has shifted from speculative valuation to tangible, on-chain utility. At the center of this technological rivalry are Sui [SUI] and Aptos [APT], two prominent networks built upon the "Move" programming language. While both projects emerged from the same technical lineage—originating from research efforts initially incubated at Meta—recent performance metrics from 2025 through early 2026 suggest that their trajectories are beginning to diverge significantly.
A Chronology of the Move Ecosystem
The narrative of Move-based blockchains began in the early 2020s, as developers sought a more secure and performant alternative to the Ethereum Virtual Machine (EVM) and its associated Solidity language. Move was designed to address critical vulnerabilities in smart contract execution, specifically focusing on resource scarcity and safety.
Aptos, led by Mo Shaikh and Avery Ching, positioned itself as a highly scalable, parallel-execution engine capable of handling tens of thousands of transactions per second. Sui, developed by Mysten Labs, launched shortly thereafter with a distinct object-centric data model. This architectural difference—Aptos focusing on a block-STM approach to parallel execution and Sui focusing on independent object management—has dictated how each network has scaled over the past eighteen months.
During the 2025 fiscal year, both networks faced severe headwinds as the broader crypto market entered a sustained bear cycle. Aptos experienced a peak-to-trough decline of approximately 80.7%, while Sui demonstrated a degree of relative stability, closing the year with a 65% decline. Analysts often attribute this divergence to the composition of their respective ecosystems; Sui’s integration of native on-chain assets and a simplified user experience appear to have fostered a more resilient base of active participants even during periods of market contraction.
Developer Activity as a Leading Indicator
In the realm of blockchain infrastructure, developer retention is widely regarded as the most reliable leading indicator of long-term network health. According to recent data synthesized by Electric Capital, a leading researcher in blockchain developer demographics, the discrepancy in talent distribution has become stark.
Sui currently reports approximately 954 monthly active developers, effectively doubling the 465 developers currently active on the Aptos network. This data is critical because developer density is not merely a vanity metric; it serves as a proxy for the speed of innovation. A higher volume of developers results in a faster cadence of product deployment, more rigorous security auditing, and a more robust pipeline of decentralized applications (dApps).
The implications of this developer gap are far-reaching. For a network to scale, it requires a diverse ecosystem of protocols—ranging from decentralized exchanges (DEXs) and lending markets to NFT marketplaces and gaming infrastructure. With nearly double the developer activity, the Sui ecosystem has been able to iterate on its protocol features more rapidly, creating a feedback loop that attracts further institutional interest and capital.
Assessing the DeFi Landscape and TVL
The competition for supremacy in the "Move" ecosystem is most visible in the Total Value Locked (TVL) metrics, which provide a snapshot of the liquidity depth within a network. As of early 2026, Sui’s TVL stands at approximately double that of Aptos. This statistical lead suggests that the infrastructure projects deployed on Sui are effectively capturing and retaining user assets.
The synergy between developer activity and TVL is clear: when builders deploy high-quality, audited, and user-friendly DeFi protocols, they solve the primary friction points for end-users. Sui’s architectural focus on object-oriented programming allows for complex DeFi operations, such as flash loans and cross-protocol liquidity management, to function with minimal latency.
In contrast, while Aptos maintains high technical throughput, it has faced challenges in converting its raw performance into sustained liquidity growth. Industry observers note that while Aptos is technically proficient, its ecosystem growth has been more sporadic. For Aptos to narrow the gap, the network must demonstrate a clear value proposition that distinguishes its performance from the rising tide of Sui’s ecosystem, perhaps through more aggressive incentives or a pivot toward specialized sectors like enterprise-grade payment rails.
The Broader Impact: Why L1 Choice Matters
The struggle between Sui and Aptos is representative of a larger shift in the blockchain sector: the "war of the virtual machines." For years, the industry was dominated by the EVM standard. However, the emergence of Move-based chains highlights a demand for better performance, safety, and scalability.

If the current trend continues, the developer-led momentum behind Sui could lead to a "network effect" where the sheer volume of dApps and liquidity creates a barrier to entry that competitors find difficult to overcome. Conversely, Aptos retains a significant advantage in its technical lineage and existing partnerships. The project’s early focus on enterprise-grade security remains a strong selling point for institutional partners looking to enter the Web3 space.
From an investor and user perspective, the implications are significant. A network with higher developer activity and a growing TVL is generally viewed as lower-risk in terms of long-term sustainability. However, the volatile nature of the cryptocurrency market means that these positions are not fixed. Technological updates, governance changes, or major project migrations could alter the landscape in a matter of months.
Future Projections and Industry Implications
As we progress further into 2026, the primary challenge for both Sui and Aptos will be moving beyond the "experimental" phase of their ecosystems. Both chains must move past technical performance and focus on mass-market adoption. This involves not only attracting developers but also ensuring that the end-user experience—wallet integration, gas fee management, and cross-chain interoperability—is seamless enough to compete with traditional financial systems.
The data suggests that while the race is far from over, Sui has successfully translated its developer-first strategy into tangible market performance. The network’s ability to maintain a higher TVL and a larger, more active developer pool provides it with a structural advantage. Aptos, while currently trailing in these specific metrics, maintains the underlying technical foundation necessary to pivot and regain lost ground.

Ultimately, the competition between these two L1s serves as a microcosm for the broader crypto industry. The "Move" language has proven to be a viable alternative to the status quo, and the ongoing battle between Sui and Aptos will likely produce innovations that benefit the entire blockchain sector, regardless of which individual network emerges as the long-term leader. Stakeholders in both ecosystems should continue to monitor developer reports, TVL fluctuations, and the deployment of new, high-utility protocols as the most accurate indicators of future success. The coming months will be decisive in determining whether Sui can cement its lead or if Aptos can leverage its foundational strengths to stage a significant recovery.