The structural landscape of the digital asset economy has undergone a profound transformation, characterized by an unprecedented divergence between the world’s leading cryptocurrency and the broader altcoin ecosystem. According to a comprehensive joint report published by on-chain analytics firm Glassnode and prominent derivatives exchange Bybit, the gap between Bitcoin and mid-to-small-cap digital assets has expanded into an unbridgeable chasm over the past two years. While Bitcoin has steadily compounded its value against a backdrop of evolving macroeconomic conditions and regulatory developments, the vast majority of alternative tokens have experienced severe, multi-year drawdowns.
Data compiled through the close of August 23 illustrates the starkness of this disparity. Over the analyzed two-year timeframe, Bitcoin recorded a net gain of approximately 28%, demonstrating resilience and sustained upward momentum despite prolonged periods of macroeconomic uncertainty. In stark contrast, the median mid-cap altcoin suffered a devastating 74% loss. This performance gap challenges historical crypto market cycles, where capital typically flowed downstream from Bitcoin into speculative assets as market maturity increased. Instead, the current cycle has been defined by a persistent flight to quality, leaving the mid-tier altcoin complex to endure repeated, compounding valuation cuts.
The Death of Traditional Altseason and Concentration of Gains
Historically, seasoned crypto market participants anticipated a predictable sequence during bull markets: Bitcoin would initiate the rally, establish a market floor, and subsequently witness capital rotation into Ethereum, large-cap altcoins, and eventually micro-cap meme tokens in a phenomenon colloquially termed "altseason." However, this cycle has completely fractured that paradigm.
Ethereum, the second-largest cryptocurrency by market capitalization, effectively flatlined over the analyzed two-year period, finishing roughly sideways. This stagnation underscored just how narrowly concentrated gains have been at the very top of the asset class. Rather than trickling down to the broader ecosystem, institutional capital and retail liquidity remained firmly anchored to Bitcoin.
Market analysts point to several structural catalysts for this phenomenon, chief among them the advent and explosive growth of spot Bitcoin exchange-traded funds (ETFs) in the United States and other global financial hubs. These regulated investment vehicles have created a continuous, passive demand pipeline for Bitcoin that has fundamentally altered supply-and-demand dynamics, isolating Bitcoin from the broader speculative impulses that historically drove altcoins.
Leverage, Speculation, and Risk Asymmetry
While institutional capital played it safe by concentrating heavily in Bitcoin, speculative retail capital sought high-beta exposure in the market’s riskiest corners. This dynamic created an unusual structural imbalance in derivatives markets.
According to the Glassnode and Bybit report, Bitcoin futures open interest hovered at a relatively conservative 2% of its total market capitalization. Conversely, speculative small-cap tokens and meme-based assets carried extreme leverage footprints. For instance, open interest for tokens such as PEPE approached a staggering 24% of its market capitalization.
This stark contrast highlights a bifurcated market ecosystem: the baseline asset class became institutionalized and de-risked, while the lower tiers of the market devolved into hyper-leveraged speculative casinos. This deep leverage concentration in small-caps left them highly vulnerable to sudden liquidations, exacerbating the 74% median drawdown calculated by the analytics firms. It is worth noting that Glassnode’s underlying metrics reflect data collected from the specific venues it tracks rather than the entirety of the global crypto economy, yet the overarching trend remains robustly supported across multiple exchanges.
Chronology of the Rally and Recent Macroeconomic Shifts
The divergence reached a critical inflection point following a series of macroeconomic catalysts, most notably shifting monetary policy expectations from the United States Federal Reserve. For months, crypto markets traded sideways within macro-driven ranges as sticky inflation data and cautious central bank commentary dampened risk appetite.
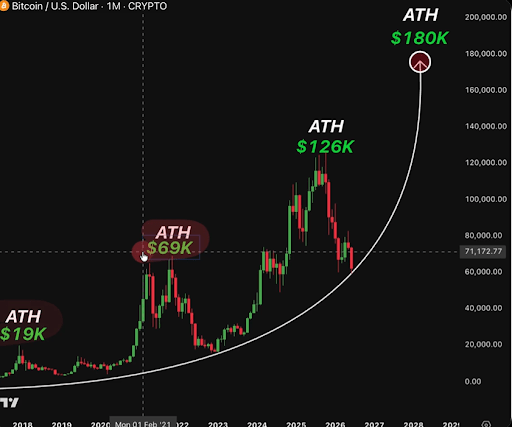
However, a sudden shift toward a dovish monetary outlook by the Federal Reserve altered market sentiment in late August. On the heels of these dovish forecasts, Bitcoin staged a dramatic technical breakout, surging decisively past the $80,000 threshold in a violent short squeeze that liquidated tens of millions of dollars in short positions.
The aggressive upside momentum in Bitcoin quickly spilled over into the broader cryptocurrency market, injecting a wave of optimism and lifting the total digital asset market capitalization by 4.6% in a single 24-hour trading window to approximately $2.85 trillion. Notably, this sudden liquidity injection briefly reignited hopes for a broader market rotation. During the sharp relief rally, several major altcoins outpaced Bitcoin’s daily percentage gains. Solana surged by approximately 10% within a single session, while layer-1 and decentralized finance protocols such as NEAR and Uniswap registered even more substantial recoveries, offering a fleeting glimpse of the market breadth that had been absent for nearly two years.
Institutional Inflows and the ETF Landscape
The structural divergence observed in secondary spot markets is starkly mirrored in the performance of regulated investment products. Institutional capital allocation clearly demonstrates a preference for primary assets, heavily skewing toward Bitcoin while leaving alternative-asset funds fighting for scraps.
Cumulative net inflows into U.S. spot Bitcoin ETFs have soared to approximately $55.2 billion, cementing Bitcoin’s status as a legitimate institutional-grade portfolio asset. Meanwhile, spot Ethereum ETFs have struggled to capture comparable enthusiasm, accumulating roughly $13.1 billion in cumulative net inflows and recently suffering a persistent, multi-day streak of net outflows.
Newer financial products, such as spot Solana ETFs, have entered the market with modest initial success, pulling in approximately $29.7 million in cumulative inflows. Market strategists suggest these figures validate the fundamental thesis of the Glassnode and Bybit collaboration: capital flows and performance are inextricably linked, and institutional investors are unwilling to diversify into lower-tier assets without clear, sustained proof of outperformance.
Implications for the Future of Crypto Market Cycles
The findings of the Glassnode and Bybit report carry significant implications for developers, traders, and long-term investors alike. As the cryptocurrency market matures, the days of indiscriminate altcoin rallies driven purely by retail speculation appear to be numbered.
The emergence of a two-tiered market—where Bitcoin acts as a macroeconomic hedge and institutional store of value, while altcoins fight for liquidity in a high-risk micro-economy—suggests that future market cycles will require much higher standards of utility, tokenomics, and organic demand for alternative assets to succeed.
Whether the late-August relief rally marks the beginning of a genuine structural rotation out of Bitcoin and into the broader altcoin ecosystem remains the defining question for traders heading into the final quarters of the fiscal year. While historical precedents suggest that extended Bitcoin dominance eventually precedes a capital trickle-down, the immense gravity of institutional ETF inflows ensures that Bitcoin will continue to dictate the terms of engagement for the foreseeable future.