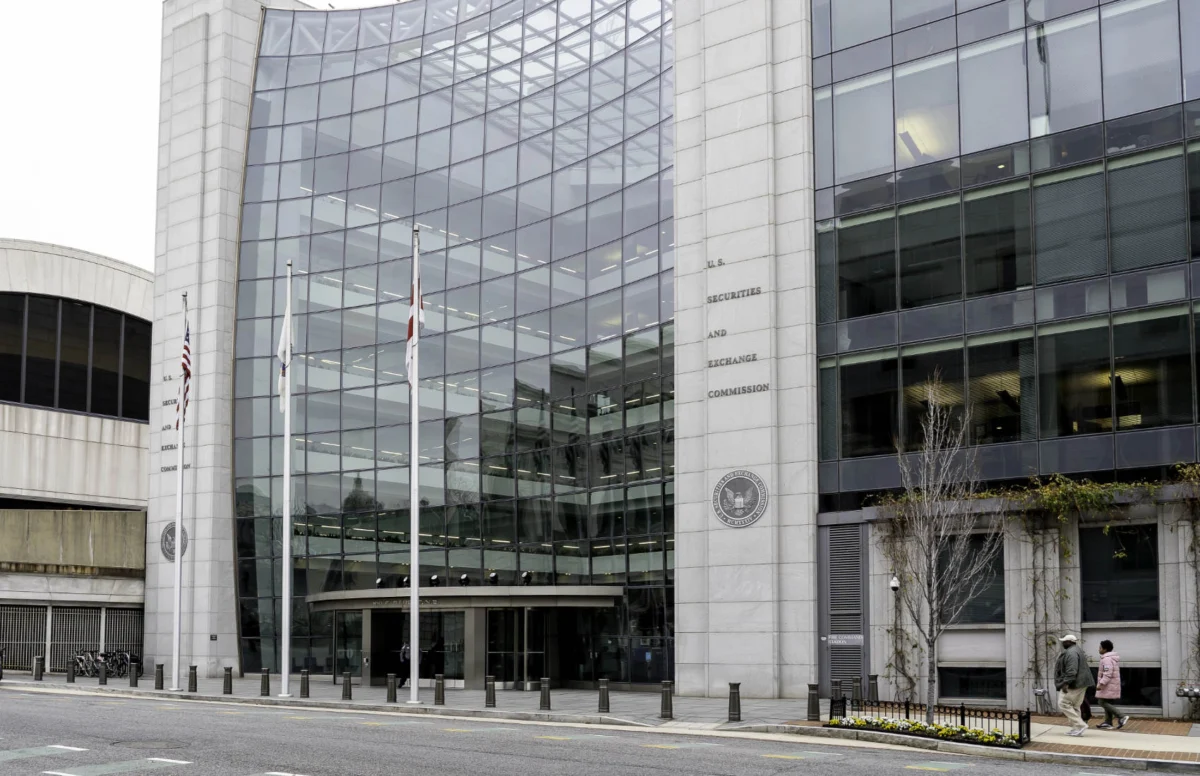
The United States Securities and Exchange Commission (SEC) has officially lifted the veil of speculation surrounding regulatory accommodations for digital assets, issuing a highly anticipated innovation exemption order. This regulatory milestone permits specific tokenized stocks—namely exchange-listed National Market System (NMS) equities—to be traded via decentralized automated market makers (AMMs). Crucially, the order grants relief without requiring these AMM venues to register formally as national securities exchanges, nor does it mandate that individual liquidity providers register as traditional securities dealers. Set for an initial trial period of five years, the order simultaneously opens a public comment window to gauge market participant feedback and evaluate ongoing systemic risks.
While the regulatory carve-out introduces a pragmatic pathway for blending traditional equity markets with decentralized finance (DeFi) infrastructure, it establishes strict operational guardrails. The SEC has imposed clear limitations on trading volumes and capped the number of individual stock symbols eligible for trading under the exemption. Furthermore, while the underlying automated market maker protocols must operate on public, permissionless blockchains, the actual trading mechanisms must incorporate permissioned layers to ensure compliance with identity verification, anti-money laundering (AML), and know-your-customer (KYC) mandates.
Background Context and Regulatory Evolution
The convergence of traditional capital markets and distributed ledger technology (DLT) has been a focal point of regulatory debate for years. Historically, the SEC has maintained a hardline stance that digital assets representing shares of public companies fall squarely under the definition of securities, subjecting issuers, brokers, exchanges, and clearing agencies to stringent federal oversight.
For institutional and retail market participants alike, the rigid structure of traditional securities laws has long created friction when attempting to leverage the speed, transparency, and composability of public blockchains. Traditional market infrastructure requires a complex, multi-tiered architecture involving central securities depositories like the Depository Trust & Clearing Corporation (DTC), registered broker-dealers, and designated clearinghouses.
In contrast, automated market makers rely on mathematical algorithms and liquidity pools rather than traditional order books, enabling continuous, peer-to-peer trading without intermediaries. By bridging these two paradigms, the SEC’s new exemption acknowledges the technological maturation of blockchain networks while striving to preserve the core investor protection mandates enshrined in federal securities laws. The five-year timeframe provides regulators with an adequate sandbox period to monitor liquidity dynamics, systemic stability, and cross-market surveillance capabilities.
Addressing the Synthetic Stock Controversy and Shareholder Rights
The introduction of the SEC’s exemption arrives amid heightened scrutiny surrounding tokenized equities, fueled by recent high-profile public disputes. Notably, a high-stakes war of words erupted between the chief executive officer of AMC Entertainment and retail-focused brokerage Robinhood regarding the nature of synthetic stocks and third-party tokenized representations. In such arrangements, digital tokens often reference an issuer’s debt or economic interest while claiming a one-to-one backing with the actual underlying equity.
To mitigate similar controversies, the SEC’s order draws a definitive line in the sand: synthetic tokens that fail to confer genuine equity rights are strictly excluded from the exemption. To qualify for the relief, tokenized instruments must convey full, uncompromised shareholder rights—including voting privileges and entitlements to corporate actions.
Moreover, the regulatory framework addresses the complex dynamics between third-party token issuers and underlying corporate entities. The rules stipulate that an AMM platform must formally notify the stock issuer thirty days prior to commencing the trading of any third-party tokenized asset. This provision ensures that the exemption is not restricted solely to issuer-sponsored tokenization initiatives; tokens issued by custodians, brokers, or centralized depositories (such as DTC-linked tokens) are eligible, provided they pass through full shareholder rights and the underlying corporate issuer does not formally object during the notification window. This mechanism balances institutional innovation with corporate governance, giving public companies a voice in how their shares are represented and traded in digital asset ecosystems.
Operational Guardrails and Compliance Frameworks
The newly established exemption framework is far from a regulatory blank check. To prevent market manipulation, excessive volatility, and systemic liquidity risks, the SEC has embedded a rigorous series of operational limitations into the order:
- Volume and Asset Caps: Trading is restricted to a carefully controlled subset of NMS stocks, with strict caps on aggregate trading volumes to prevent localized DeFi protocols from destabilizing primary price discovery on traditional national exchanges.
- Permissioned Access on Permissionless Rails: While the settlement and execution logic reside on public, permissionless blockchain infrastructure, access to the liquidity pools and trading interfaces must enforce robust compliance checks. This ensures that anonymous or sanctioned entities cannot bypass securities laws.
- Issuer Veto Power: The mandatory thirty-day notification period gives stock issuers meaningful oversight, allowing corporations to challenge unauthorized or potentially manipulative tokenization schemes before trading begins.
- Comprehensive Audit Trails: Platforms utilizing the exemption must maintain transparent, verifiable records of transactions to assist regulatory bodies in monitoring market integrity and enforcing compliance.
Market Implications and Industry Outlook
The SEC’s innovation exemption represents a watershed moment for the digital asset industry, signaling a potential shift from enforcement-heavy oversight to structured regulatory accommodation. For decentralized finance developers and fintech innovators, the order provides long-sought legal clarity, reducing the existential regulatory risk that has historically driven blockchain projects out of the United States.
However, traditional financial institutions and established market infrastructure providers will likely analyze the ruling with cautious scrutiny. The integration of public blockchains into mainstream equity trading challenges established clearing and settlement monopolies, potentially accelerating the modernization of legacy financial plumbing. At the same time, the requirement to pass through full shareholder rights and honor corporate vetoes means that tokenization platforms must build sophisticated compliance and administrative back-ends.
As the five-year trial period commences and the public comment period unfolds, market participants across the traditional and decentralized financial landscapes will closely monitor how these tokenized equity pools perform under real-world market conditions. The success or failure of this regulatory experiment could ultimately dictate the blueprint for the future digitization of global capital markets.