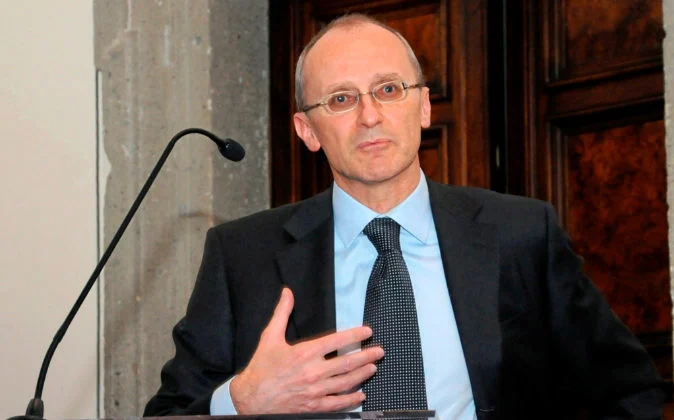
The ongoing discourse surrounding the regulation of digital assets and financial technology has reached a critical juncture, with European banking authorities advocating for a departure from extreme policy positions. Speaking at the Copenhagen Business School on Friday, Andrea Enria, the then-Chair of the European Banking Authority (EBA), challenged the prevailing binary debate that has dominated financial policy circles. Enria’s remarks served as a significant intervention in the global conversation regarding how sovereign entities should handle the rapid expansion of blockchain-based startups and decentralized financial services.
The Dichotomy of Regulation
For years, the regulatory landscape regarding cryptocurrencies and fintech has been characterized by what Enria termed a "Manichean" approach—a rigid, two-sided conflict. On one side are proponents of a "regulate and restrict" strategy, which seeks to prohibit any financial initiative that deviates from traditional, incumbent-led banking standards. This approach often views innovation through a lens of suspicion, prioritizing the stability of legacy systems over the potential benefits of technological advancement.
On the other side of the spectrum lies the "laissez-faire" philosophy. This school of thought suggests that financial operations should proceed with minimal oversight, placing the burden of risk exclusively on the participants. While this fosters a sandbox-like environment for developers, Enria cautioned that it leaves markets vulnerable to systemic fragility, fraud, and a lack of investor protection. Such an environment, he argued, ultimately discourages institutional capital, which requires a foundation of legal certainty to enter the market at scale.
Chronology of EBA’s Fintech Engagement
The European Banking Authority has been navigating the complexities of digital finance for years, aiming to reconcile innovation with consumer protection. The organization’s engagement with the sector follows a distinct timeline of evolving oversight:
- 2014-2015: The EBA issued its first warnings regarding the risks of virtual currencies, focusing primarily on consumer awareness and the lack of AML (Anti-Money Laundering) safeguards.
- 2017: As the Initial Coin Offering (ICO) boom gained momentum, the EBA intensified its monitoring, recognizing that digital assets were transitioning from niche experimental projects into significant financial instruments.
- 2018: The address at the Copenhagen Business School marked a pivotal shift in the EBA’s rhetoric, moving from mere observation and warning to proposing a "proportional and technologically neutral" framework.
- 2019-2020: These principles began to influence the early discussions surrounding what would eventually become the Markets in Crypto-Assets (MiCA) regulation, aiming to create a comprehensive legal structure for the EU.
Proportionality and the Banking Perimeter
Central to Enria’s thesis is the concept of a "proportional" regulatory perimeter. He argued that regulators must not reflexively extend the full weight of bank-like supervision to every fintech startup simply because they compete with traditional banks in specific segments. Instead, Enria proposed a tiered system of oversight.
Under this model, functions that are essential to systemic stability—such as the provision of liquidity during crises and traditional lending—should remain strictly reserved for banks. These activities require the highest levels of oversight due to their potential impact on the broader economy. Conversely, services such as payments, electronic money issuance, and digital asset custody do not necessarily require the same regulatory apparatus. By allowing these non-essential functions to operate under a lighter, more agile framework, regulators can foster competition without compromising the integrity of the banking system.
The Economic Case for Neutrality
Enria’s advocacy for a "technologically neutral" approach addresses the inherent bias regulators often hold toward the status quo. If regulations are designed around specific technologies, they risk becoming obsolete as soon as those technologies evolve. By focusing on the function of a service—rather than the technical architecture behind it—regulators can create a sustainable environment that accommodates both legacy institutions and decentralized innovators.
Data from the European Commission during this period suggested that while the fintech sector was growing at a compound annual rate of over 15%, the lack of clear, harmonized regulation across the Single Market was acting as a significant barrier to entry. For a startup based in one EU member state, the prospect of navigating 27 different regulatory environments proved prohibitively expensive, effectively stifling cross-border scalability.
Broader Implications for the Single Market
The EBA’s roadmap, as outlined by Enria, aimed to provide a path for fintech firms to scale across the European Single Market. The implications of this are twofold. First, for consumers, a unified regulatory standard ensures that services meet a baseline of security and reliability, regardless of which EU country they originate from. Second, for the market, it creates a "level playing field" where innovation is not punished by excessive bureaucracy, nor is it left unchecked to the detriment of market integrity.
Critics of this approach often point to the "regulatory arbitrage" that could occur if different regions of the world adopt vastly different standards. However, Enria’s vision suggests that the EU could lead by example. By setting a standard that is neither too restrictive nor too permissive, the European Union can position itself as a global hub for responsible financial innovation. This strategy hinges on the ability of national competent authorities to cooperate effectively—a task that remains a significant challenge within the fragmented European financial landscape.
Analyzing the "Wait-and-See" Risk
Despite the logical appeal of Enria’s proposal, the transition from policy theory to implementation remains a hurdle. Financial authorities have historically struggled with the speed of digital evolution. The "wait-and-see" approach, while sometimes prudent, can result in regulators being perpetually reactive, constantly playing catch-up to the latest market trends.
The adoption of Enria’s proportionality principle requires a fundamental shift in institutional culture. It demands that regulators possess a deep, technical understanding of blockchain and smart contracts, rather than relying solely on traditional legal frameworks. If successful, this shift could prevent the "brain drain" of talent to more permissive jurisdictions, such as Switzerland or Singapore, while simultaneously ensuring that the European financial system remains resilient against the volatility inherent in emerging asset classes.
The Future of Fintech Supervision
Andrea Enria’s call for a balanced approach represents a move toward maturity in the governance of digital assets. By rejecting both the total prohibition of decentralized innovation and the abandonment of regulatory duty, the EBA sought to carve out a middle path. This path recognizes that the future of finance is not a zero-sum game between traditional banks and fintech startups, but rather an ecosystem that requires the stability of the former and the agility of the latter.
As the financial sector continues to digitize, the principles articulated by Enria remain highly relevant. The ongoing challenge for policymakers will be to ensure that these regulations are not static. To be truly effective, the regulatory perimeter must be flexible enough to adapt as decentralized finance (DeFi) and other innovations continue to challenge the definitions of banking, money, and ownership. The ultimate goal, as Enria suggested, is not to protect the institutions of the past, but to create a robust financial infrastructure capable of supporting the economic activities of the future.
In conclusion, the discourse initiated by the EBA in 2018 serves as a foundational chapter in the development of European digital asset policy. By advocating for a nuanced, risk-based approach, the authorities aimed to catalyze growth while maintaining the high standards of protection that characterize the European financial market. The continued success of this vision depends on the sustained commitment of EU member states to harmonize their efforts, ensuring that innovation can thrive within a framework that is both secure and transparent.