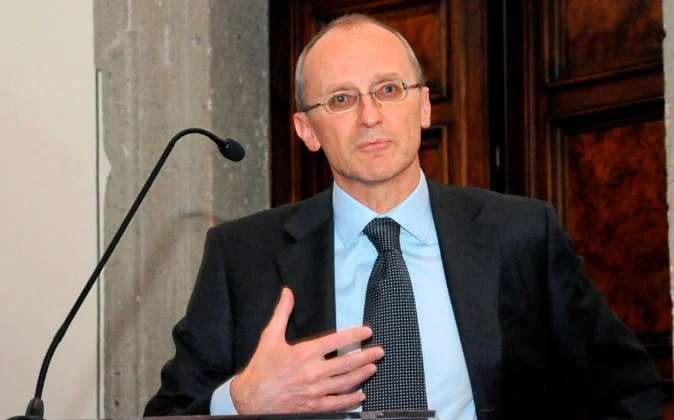
The landscape of global financial regulation is currently undergoing a period of intense scrutiny as traditional banking authorities grapple with the rapid ascent of decentralized finance and digital assets. Andrea Enria, serving as the head of the European Banking Authority (EBA), recently delivered a significant address at the Copenhagen Business School that signals a departure from the binary regulatory philosophies currently dominating the discourse in Brussels and beyond. Challenging the prevailing "Manichean" dichotomy of either total restriction or unchecked laissez-faire, Enria advocated for a middle-ground approach that prioritizes technological neutrality and proportionate oversight.
The Current Regulatory Impasse
For several years, financial regulators have struggled to classify cryptocurrency startups and blockchain-based financial service providers within existing legal frameworks. The debate has largely been polarized between two camps. On one side are the proponents of "regulate and restrict," who argue that any entity operating within the financial sector must adhere to the stringent capital requirements and compliance standards designed for traditional commercial banks. This approach, while theoretically protective of consumers, has been criticized for stifling innovation and creating insurmountable barriers to entry for early-stage fintech firms.
Conversely, the "laissez-faire" camp argues that digital asset markets should remain free from government intervention, operating on the principle of caveat emptor—buyer beware. However, as Enria noted, this lack of oversight carries significant risks. Without a base level of legal protection, these markets struggle to attract institutional capital, which requires regulatory certainty to justify investment. By rejecting both extremes, Enria has positioned the EBA as a mediator capable of fostering an environment where innovation is encouraged, but systemic risk is mitigated.
A Tiered Regulatory Framework
The core of Enria’s proposal lies in a tiered supervision model. He argues that the nature of the service provided should dictate the level of oversight, rather than the technology utilized. According to this framework, functions inherently linked to the stability of the financial system—such as the provision of credit, liquidity management in crisis situations, and deposit-taking—must remain the exclusive domain of regulated banking institutions. These activities, which carry systemic risk, warrant the robust, "enhanced" supervision that currently governs the European banking sector.
However, Enria suggests that other activities, such as electronic money issuance and payment processing, can be safely unbundled from the traditional banking license. By allowing non-bank intermediaries to provide these services, the EU could potentially lower costs for consumers and increase competition in the fintech space. This "activity-based" rather than "entity-based" regulation would prevent a "one-size-fits-all" approach that currently threatens to stifle small-scale innovation under the weight of massive bureaucratic compliance requirements.
Chronology of the European Banking Authority’s Fintech Pivot
The EBA’s recent stance did not emerge in a vacuum. The organization has been methodically developing its roadmap for digital finance since 2017, when it first established a Fintech Knowledge Hub to monitor developments in the market.
- Early 2017: The EBA publishes a Discussion Paper on the approach to Fintech, identifying the key challenges for regulators, including cybersecurity, money laundering risks, and the impact of artificial intelligence.
- Late 2017: The EBA establishes the "Fintech Knowledge Hub," a platform designed to facilitate a continuous dialogue between regulators and fintech companies, ensuring that policymakers are aware of technological trends.
- Early 2018: During the Copenhagen Business School seminar, Andrea Enria publicly articulates the necessity of a "proportionate" regulatory perimeter, marking a shift toward active engagement with the sector.
- Post-2018 Context: This strategic pivot laid the groundwork for the European Union’s later, more comprehensive legislative frameworks, including the Markets in Crypto-Assets (MiCA) regulation, which sought to harmonize rules across member states.
Data-Driven Implications for European Startups
The economic implications of Enria’s proposal are significant. According to reports from the European Commission, the fintech sector in Europe has faced a "fragmentation" problem. Startups that grow in one EU member state often struggle to scale into others due to varying local interpretations of financial regulation.
Data from the European Fintech Association suggests that over 60% of blockchain-based startups cite regulatory uncertainty as the primary obstacle to raising venture capital. When a startup operates in a "grey zone," institutional investors—who are often risk-averse—tend to hold back. By clarifying that specific services do not require full banking licenses, the EBA’s approach provides the legal clarity necessary to unlock capital flows. Proponents argue that if the EU can successfully implement a proportionate regime, it could potentially capture a larger share of the global blockchain market, which is currently seeing intense competition from jurisdictions like Singapore and Switzerland.
Official Responses and the Challenge of "Status Quo" Bias
Enria’s remarks have been interpreted as a direct critique of the "status quo bias" inherent in many regulatory institutions. When an agency is tasked with protecting financial stability, the natural institutional reflex is to regulate aggressively to prevent failure. However, Enria warned that this bias can be destructive. An excessive extension of the regulatory perimeter—pulling innovative startups into the same stringent oversight as major retail banks—serves only to protect incumbents from competition.
Industry analysts have generally lauded this shift in tone. Representatives from various European fintech associations have noted that if authorities follow the "technologically neutral" path, it would allow the industry to experiment with decentralized ledger technology (DLT) without the fear of being shut down by regulators who may not fully grasp the underlying code. However, some traditionalists remain cautious. Critics within the banking sector argue that even payment services, if allowed to scale massively without bank-like oversight, could lead to "shadow banking" risks if the payment providers are not adequately capitalized.
The Path Forward: Towards a Single Market for Fintech
The EBA’s roadmap, as outlined by Enria, is not merely about deregulation; it is about scaling. The ultimate goal is to allow fintech firms to offer their services across the entire European Single Market, providing benefits to all EU citizens through cheaper and faster cross-border payments.
To achieve this, the EBA continues to work on standardizing supervisory practices. The challenge remains in the implementation phase. While Enria’s vision is clear, the practical application requires all EU member states to align their national competent authorities (NCAs) with the EBA’s vision. If successful, the EBA’s framework could serve as a global gold standard for how to integrate decentralized, innovative financial technologies into a legacy banking structure without sacrificing the safety of the broader financial ecosystem.
Analysis: Balancing Innovation and Stability
The pragmatic approach advocated by Andrea Enria highlights the central tension of modern financial governance: how to encourage the disruptive potential of new technologies while maintaining the public trust that the banking system relies upon. By separating "essential" banking functions from "innovative" services, the EBA is attempting to preserve the core of the financial system—lending and deposit-taking—while creating a sandboxed environment for fintechs to flourish.
If this policy of proportionality is adopted and consistently applied, the long-term impact on the European economy could be transformative. It would signal to global markets that the EU is "open for business" in the digital asset space, potentially stemming the brain drain of fintech talent to North America and Asia. Ultimately, Enria’s argument is that regulation should be a facilitator of market integrity rather than a gatekeeper that guards the status quo. As the digital economy continues to evolve, the ability of regulators to remain "technologically neutral" will be the defining factor in determining whether the next generation of financial infrastructure is built in Europe or elsewhere.